Frozen Pipes and Ice Dams: Iowa Winter Home Claims
Do Iowa home policies cover frozen pipes and ice dams? What is usually paid, what gets denied, and a winter checklist to help prevent water damage claims.
By Kurt Lease
The River Bend Agency
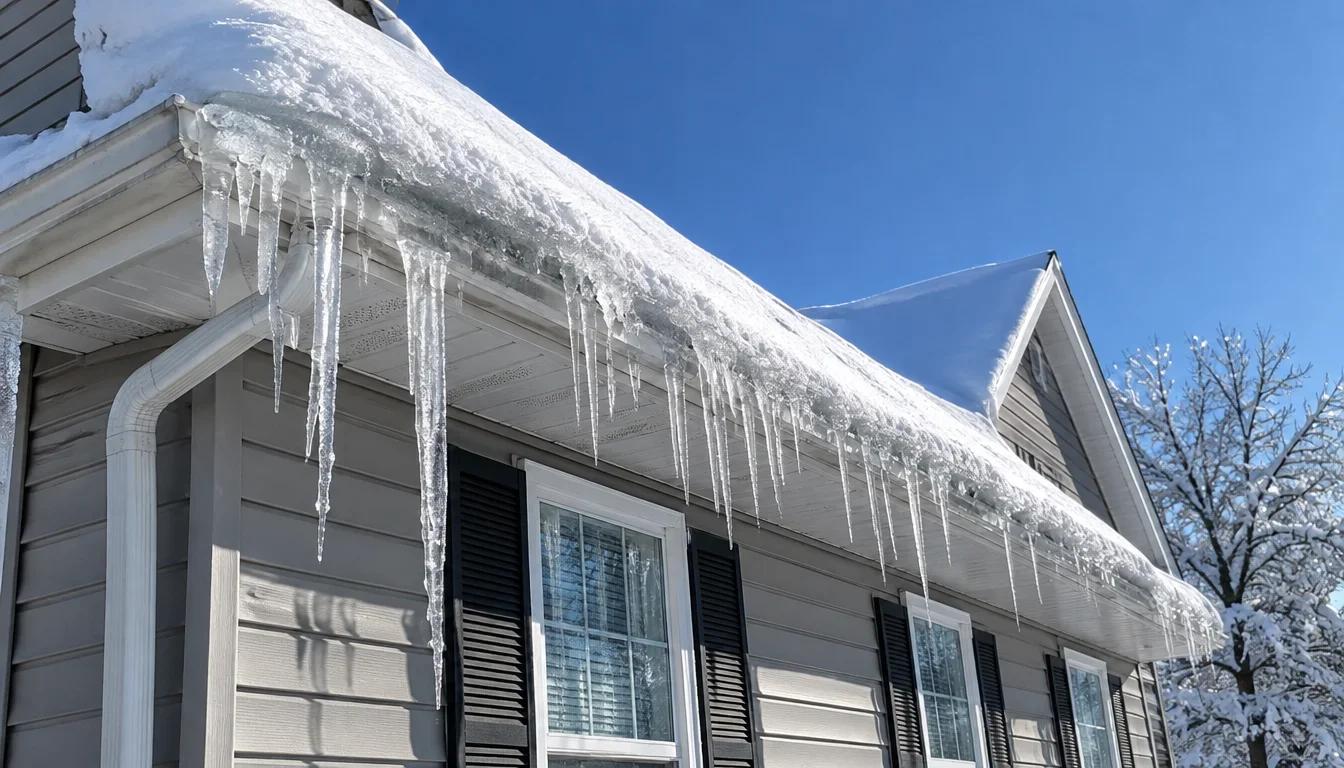
A Quad Cities cold snap does its damage quietly. A pipe in an outside wall freezes overnight, splits, and nobody notices until it thaws and starts spraying into the drywall. Or snow on the roof melts, refreezes at the gutter, and water backs up under the shingles and into a bedroom ceiling.
Both are common Iowa winter home claims. Whether your policy pays depends on what caused the water and what you did before it happened. Here is how frozen pipes and ice dams are usually handled, and what to do now so you are not testing it in January.
Why water claims cost so much
Water damage and freezing made up about 27.6 percent of homeowners losses nationally in 2022, second only to wind and hail. From 2018 to 2022 the average claim in that category was about $13,954, according to the Insurance Information Institute. That figure is national, but the pattern holds here: water travels, soaks into flooring and insulation, and turns a small leak into new drywall, new floors and a few weeks of drying fans.
Frozen pipes: usually covered, with conditions
Most homeowners policies cover sudden and accidental water damage, and a pipe that freezes and bursts usually fits. The policy typically pays to repair the damage the water caused, such as walls, floors, ceilings and damaged belongings. Repairing the pipe itself may be handled differently.

The conditions are where claims get complicated:
- Heat in the house. Many policies expect you to keep reasonable heat on. If a house sits empty with the furnace off and pipes freeze, the claim can be denied.
- Vacancy. A home left vacant for a long stretch, often 30 or 60 days depending on the policy, can lose some water damage coverage. If you winter somewhere warmer, tell your agent.
- Slow leaks. A drip that went on for months is treated as wear or maintenance, not a sudden event. That is usually excluded.
The American Red Cross suggests keeping the thermostat no lower than 55 degrees when you are away. That one habit removes the most common reason a frozen pipe claim gets questioned.
Ice dams: the roof and the damage are two separate questions
An ice dam forms when heat from the house melts snow on the upper roof, the water runs down, and it refreezes at the colder edge. The ridge of ice holds back more meltwater, which works under the shingles.
Coverage usually splits this way:
- Interior water damage from an ice dam, like stained ceilings, wet insulation and damaged walls, is often covered.
- The ice dam itself, and the cost to remove it, often is not, unless it is causing active damage.
- Gutters and roofing may or may not be covered, depending on the policy and whether the damage is sudden or the result of an aging roof.
Older roofs matter here. Some policies pay roof damage based on depreciated value, which can leave a gap. It is worth knowing which kind you have before the first big snow.
What is usually not covered
A few winter claims tend to fall outside a standard policy:
- Sewer or drain backup when snowmelt overwhelms the system, unless you added a water backup endorsement.
- Rising water or snowmelt flooding from outside, which needs separate flood insurance.
- Damage from long-term neglect, like a roof that leaked for several seasons.
Our Bettendorf home insurance page explains the backup endorsement and other common add-ons.
A short winter checklist
None of this is complicated, and most of it takes one weekend in November:
- Disconnect garden hoses and shut off outside faucets from the inside valve if you have one.
- Wrap exposed pipes in unheated spaces like crawl spaces, garages and outside walls with foam sleeves.
- On the coldest nights, open cabinet doors under sinks on outside walls and let a faucet drip.
- Keep the heat at 55 degrees or higher, even when you travel.
- Know where your main water shutoff is, and make sure everyone in the house does too.
- Clear gutters before snow, and look at attic insulation and ventilation if you have had ice dams before.
- If you leave for more than a few days, ask a neighbor to check the house.
If it happens anyway
Shut off the water at the main valve. Take photos and video of the damage before you clean up. Start drying things out and move what you can, since your policy expects you to prevent further damage. Keep receipts for fans, dehumidifiers and any emergency repairs. Then call to start the claim.

Review your policy before the first cold snap
Winter is a good time to check three things: your water damage terms, whether you have a water backup endorsement, and how your roof is covered. Ten minutes on the phone now is easier than reading exclusions with a wet ceiling.
Brightway Insurance, The River Bend Agency is at 2395 Tech Dr Ste. 5B in Bettendorf, serving homeowners in Bettendorf and across the Quad Cities. Call (563) 594-6628 or visit the agency's home page to review your coverage. Flooding from rising water is a separate risk, so see the agency's guide to flood insurance in Bettendorf.
This article is general information, not a coverage promise. What any policy pays depends on its terms, limits and exclusions.
More from The River Bend Agency
Car Insurance for Quad Cities Commuters Crossing Into Illinois
Commuting from Bettendorf into Illinois? How Iowa and Illinois minimums compare, what your policy does across the river, and the gaps to check at renewal.
Read →Iowa Car Insurance Requirements for Bettendorf Drivers
Iowa's 20/40/15 minimum, built-in uninsured motorist coverage, proof-of-insurance rules and fines, and what the state minimum leaves out for Bettendorf drivers.
Read →Flood Insurance in Bettendorf, IA: Mississippi River Risk
Flood insurance in Bettendorf, IA: why home policies exclude river flooding, what NFIP covers, the 30-day wait, and how to check your FEMA flood zone.
Read →