Flood Insurance in Bettendorf, IA: Mississippi River Risk
Flood insurance in Bettendorf, IA: why home policies exclude river flooding, what NFIP covers, the 30-day wait, and how to check your FEMA flood zone.
By Kurt Lease
The River Bend Agency
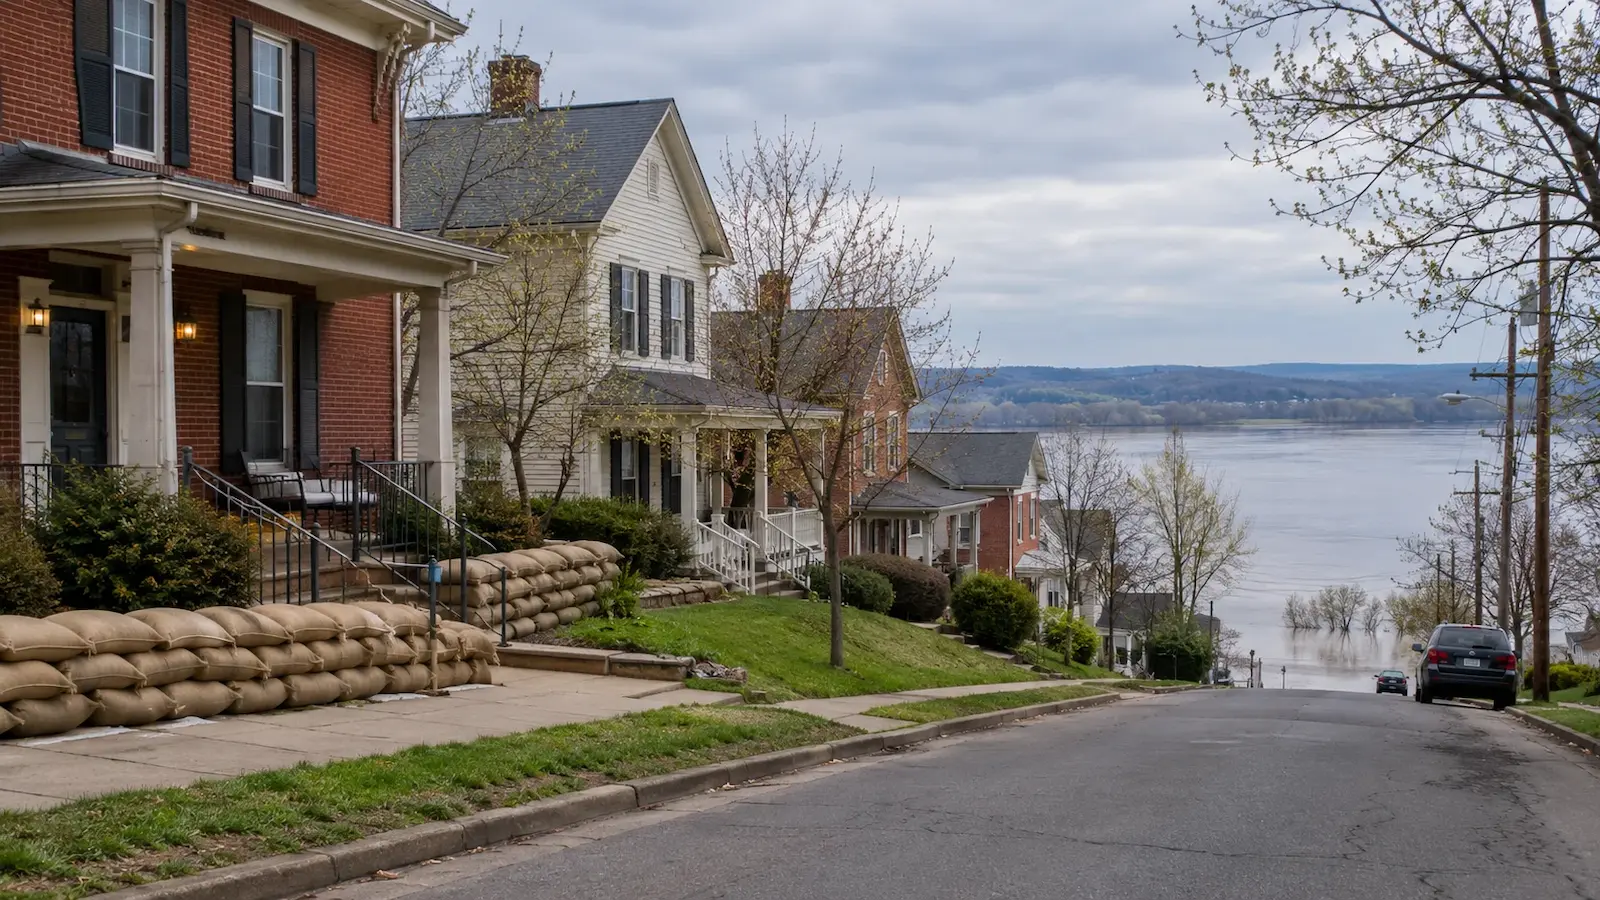
Most Bettendorf homeowners know the Mississippi can rise. Fewer know that the homeowners policy in the kitchen drawer almost certainly won't pay a dime when it does. Flood is its own coverage, sold as its own policy, and it has a waiting period that catches people off guard every spring.
This guide covers what flood insurance in Bettendorf, IA actually pays for, how to check your own address, and what to ask before the river is in the forecast.
The river sets records here
In spring 2019 the Mississippi crested at 22.70 feet at the Rock Island gauge on May 2, the highest reading on record there, according to the National Weather Service in Davenport. It beat the 1993 mark, and the river stayed above flood stage for weeks.
Bettendorf's floodwall held through most of it. Davenport, right next door, had a temporary barrier fail and saw several downtown blocks go under. Crews in Bettendorf still ran pumps at River Drive to keep water out.
So the risk is real, but it is uneven. A house a few blocks from the river on higher ground and a house near Duck Creek or Crow Creek can have very different flood exposure. That is why the address matters more than the zip code.
Your homeowners policy almost certainly excludes flood
Standard homeowners policies exclude damage from surface water and rising water. If the river or a creek comes over its banks and into your basement, that is flood, and it needs a flood policy.
A few related things are often confused with flood:
- Sewer or drain backup. Water coming up through a floor drain is usually covered only if you added a water backup endorsement to your home policy. It is separate from flood coverage.
- A burst pipe. Sudden water from inside the house is typically a homeowners claim, not a flood claim.
- Heavy rain seeping through a foundation. This one depends on wording and is often excluded under both. Ask before you assume.
Our Bettendorf home insurance page walks through backup endorsements and the other add-ons people ask about most.
How NFIP flood insurance works
Most flood policies in Iowa are written through the National Flood Insurance Program, run by FEMA and sold through local agents. Some private insurers write flood too, and depending on the home they can be worth pricing next to NFIP.
The NFIP basics, from FloodSmart.gov:
- Building coverage goes up to $250,000 for a home.
- Contents coverage goes up to $100,000 for your belongings.
- Renters can buy contents coverage on its own.
- Coverage usually starts 30 days after you buy. The main exception is a policy bought when you close on, refinance or extend a mortgage.
That 30-day wait is the part that trips people up. Once a crest forecast is on the evening news, it is usually too late for this season.
The basement problem
If there is one thing to know before buying, it is this: NFIP policies cover a basement only in a limited way.

Building coverage includes things like the furnace, water heater, electrical panel, sump pump and the foundation itself. But finished walls, carpet and most of what you store down there are generally not covered. A finished basement full of furniture can be the biggest loss in a flood and the least covered part of the house.
If your basement is finished, ask how a private flood policy handles it, move what you can off the floor, and keep the appliances that are covered on blocks or platforms where practical.
Do you need it if you're not in a flood zone?
Lenders require flood insurance when a home with a federally backed mortgage sits in a FEMA high-risk zone. Outside those zones it is optional.

Optional is not the same as safe. FEMA reports that more than 20 percent of NFIP claims come from outside high-risk areas. And policies for homes in lower-risk areas tend to cost less, so it is worth getting a real number instead of guessing.
To check your address, use the FEMA Flood Map Service Center. Type in your street address and look at the zone. Then call us, because the map is a starting point and not a price.
What to ask before you buy
A short list for the call:
- What flood zone is my address in, and is there an elevation certificate on file?
- What would NFIP cost, and what would a private flood policy cost?
- How does each one handle my basement?
- Can I add contents coverage, and how much makes sense for what I own?
- If I already have a water backup endorsement, is the limit high enough?
Kurt Lease is licensed in Illinois as well as Iowa, so the same questions apply to homes across the river. More on the neighborhoods we serve is on our Bettendorf insurance page.
Getting it done before spring
Flood insurance in Bettendorf is cheapest to think about in the fall, when the river is quiet and the 30-day clock doesn't matter. Pull up your address on the FEMA map, check your basement, and get a quote you can compare.
Brightway Insurance, The River Bend Agency is at 2395 Tech Dr Ste. 5B in Bettendorf. Call (563) 594-6628 or start with the agency's home page to request a quote. Winter brings its own water risks, so see the agency's guide to frozen pipes and ice dams.
This article is general information, not a coverage promise. What any policy pays depends on its terms, limits and exclusions.
More from The River Bend Agency
Car Insurance for Quad Cities Commuters Crossing Into Illinois
Commuting from Bettendorf into Illinois? How Iowa and Illinois minimums compare, what your policy does across the river, and the gaps to check at renewal.
Read →Iowa Car Insurance Requirements for Bettendorf Drivers
Iowa's 20/40/15 minimum, built-in uninsured motorist coverage, proof-of-insurance rules and fines, and what the state minimum leaves out for Bettendorf drivers.
Read →Frozen Pipes and Ice Dams: Iowa Winter Home Claims
Do Iowa home policies cover frozen pipes and ice dams? What is usually paid, what gets denied, and a winter checklist to help prevent water damage claims.
Read →